If you hire freelancers in Germany, you need to keep false self-employment in mind. Otherwise you risk large back payments and, in the worst case, criminal proceedings. This guide explains how auditors spot false self-employment, what happens if things go wrong and how the status determination procedure works. You will also find a case from the car industry, practical tips and a checklist for your projects.
Legal position as of October 2026. This guide gives an overview and is not legal advice.
1. What Is False Self-Employment?
False self-employment (also called bogus or pseudo self-employment, in German: Scheinselbstständigkeit) exists when someone is self-employed on paper but in fact works like an employee. Legally, they are then in dependent employment. The client should have registered them as an employee for social security.
The benchmark in Germany is Section 7(1) of Book IV of the German Social Code (SGB IV). It defines employment as non-self-employed work, in particular in an employment relationship. Indicators are working under instructions and being integrated into the instructing party’s work organization. The German Pension Insurance (Deutsche Rentenversicherung) defines the term as follows (DRV glossary, in German):
“Pseudo-self-employed workers are persons who formally appear as self-employed (contractors) but are in fact dependent employees within the meaning of Section 7(1) SGB IV.” (our translation)
Is False Self-Employment Dangerous?
Yes, both for freelancers and for companies that hire them. If an audit finds that a freelancer was actually employed, the collaboration is treated as employment retroactively. The client then has to pay social security contributions after the fact, and further consequences can follow (section 3).
The risk is real: the German Pension Insurance audits every employer at least every four years (Section 28p SGB IV).
Who Checks for False Self-Employment?
A review can be triggered in several ways:
- Employer audit: If the German Pension Insurance assesses an assignment differently than you during its audit, it will claim the contributions. As a client, you therefore have to check yourself, like any employer, whether a contractor is employed by you or self-employed (DRV glossary, in German).
- Health insurance fund: As the body that collects social security contributions, the health insurance fund can also decide on compulsory insurance (Section 28h SGB IV).
- Customs: The customs unit for undeclared work (Finanzkontrolle Schwarzarbeit, FKS) investigates suspected false self-employment. Lawmakers expanded its powers for this in 2019. The explanatory memorandum to the bill put it plainly: false self-employment leaves the supposedly self-employed without social protection and puts a strain on the social security systems (Bundestag printed paper 19/8691, in German).
- Tax office: During a payroll tax audit, the tax office can classify a freelancer as an employee for tax purposes.
- Labor court: If a freelancer sues, for example for permanent employment or protection against dismissal, the labor court decides whether an employment relationship exists.
- Status determination procedure: You and the freelancer can have the status clarified by the clearing office of Deutsche Rentenversicherung Bund. Section 4 explains how.
2. What Criteria Determine False Self-Employment?
There is no black or white. The German Pension Insurance decides based on an overall assessment of all circumstances of the individual case (Section 7a(2) SGB IV). The law has no checklist you can simply tick off, only indicators and comparable cases to guide you.
Auditors look at the contracts and at how the work is actually done day to day. If the two differ, the Federal Social Court gives priority to the practice actually lived (Federal Social Court, judgment of 4 June 2019, B 12 R 11/18 R). The following criteria, among others, play a role:
-
No staff of their own. Working alone does not make someone falsely self-employed. Having employees, however, points to a business of their own. Watch out for a common mix-up: self-employed people who have no employees subject to social insurance and work permanently and mainly for one client can be subject to compulsory pension insurance as self-employed persons (Section 2 sentence 1 no. 9 SGB VI). That is not false self-employment. In that case, the self-employed person pays the contributions themselves (Section 169 SGB VI).
-
Long assignments without a clear end. A project with a goal and a set duration fits a freelance assignment. If a freelancer works for the same company for years without a defined project, it looks more like a job.
-
Only one client. If a freelancer earns almost all of their revenue with one client, there is no entrepreneurial presence on the market. That alone does not make it false self-employment, but it reinforces other signs.
-
Fixed working hours. Self-employed people owe an agreed service, not attendance. Fixed appointments such as meetings are normal. Fixed hours, time tracking like employees or vacation requests, on the other hand, fit an employment relationship.
-
Work instructions by email or chat. Self-employed people decide for themselves how to reach a goal. Under a contract for work, the contractor owes an agreed result, not just an activity. Ongoing individual instructions point to dependence on instructions, even if they arrive digitally and the freelancer works remotely.
-
Low hourly rates. According to the Federal Social Court, a fee well above the salary of comparable employees that allows for private provision is a weighty indicator of self-employment (Federal Social Court, judgment of 31 March 2017, B 12 R 7/15 R). A rate at employee level does not provide this indicator. The fee alone does not decide the case, though. Nor can a client buy its way out of compulsory insurance by adding a premium to the usual hourly rate (Federal Social Court, B 12 R 11/18 R).
-
Involvement in decisions and processes. Is the freelancer bound by requirements on materials, staff or equipment? Are they scheduled into team processes like an employee? Self-employed people are responsible for their result and decide on the way to get there.
Are Clearer Rules Coming?
Companies that work with freelancers have been calling for clearer rules for years. The German Association of Founders and Self-Employed People (VGSD) campaigns for more legal certainty in status determination (VGSD, in German). We at ElevateX also consider more transparency inevitable.
A reform is in the works: a 2026 draft bill from the Federal Ministry of Labour and Social Affairs would introduce an additional “new self-employment” status from 2028, combined with compulsory pension insurance (LTO, in German). As of October 2026, nothing has been decided. Until new rules are adopted, the rules described in this guide apply.
3. What Are the Consequences of False Self-Employment?
Any self-employed person who takes on contract work can be affected, especially freelancers. If an audit finds employment, this has consequences for both sides.
What Do Freelancers Risk?
On the one hand, a freelancer gains rights. If they are also an employee under labor law (Section 611a of the German Civil Code (BGB)), they are entitled to protection against dismissal and paid vacation, for example. On the other hand, they face drawbacks.
This hits many freelancers hard, because most of them deliberately chose self-employment and, for example, built their retirement provision around it. A forced employment relationship can upset those plans.
Then there is VAT: if the tax office also classifies the freelancer as an employee, they were not acting as a business for this assignment. They still owe the VAT shown on their invoices. They can only correct it with the tax office’s consent, and only if the client has not deducted the input tax or has repaid it (Section 14c(2) of the German VAT Act (UStG)).
What Risks Do Clients Face?
For the client, all obligations of an employer apply retroactively. The main consequences:
- Back payment of contributions: The employer owes the total social security contribution, meaning both the employer’s and the employee’s share (Section 28e SGB IV). Claims only become time-barred four years after the end of the year in which the contributions were due. For contributions withheld intentionally, the period is 30 years (Section 25 SGB IV).
- Bearing the employee’s share: The employer can only recover the employee’s share through deductions from wages. Missed deductions are generally only allowed in the next three wage payments (Section 28g SGB IV). For past years, the employee’s share therefore usually stays with the client.
- Late payment surcharges: 1 percent of the outstanding contributions is charged for each month or part of a month in arrears. The surcharges only lapse if the client can credibly show that they were unaware of the payment obligation through no fault of their own (Section 24 SGB IV).
- Payroll tax: The tax office can hold the client liable for payroll tax that was not withheld. To that extent, client and freelancer are jointly and severally liable (Section 42d of the German Income Tax Act (EStG)).
- Input tax: If the freelancer was not acting as a business for VAT purposes, their invoices do not entitle the client to deduct input tax (Section 15 UStG). The client has to repay input tax already deducted.
- Fines and criminal penalties: Even contributions withheld through gross negligence can lead to a fine of up to 50,000 euros (Section 8 of the Act to Combat Undeclared Work (SchwarzArbG)). Withholding contributions intentionally is a criminal offense. It is punishable by a fine or up to five years in prison, and more in particularly serious cases (Section 266a of the German Criminal Code (StGB)).
- Labor law: If the freelancer is also an employee under labor law, they have the same rights as your employees.
Case Study: Sham Contracts at a Car Manufacturer
A case at a major German car manufacturer shows how quickly an assignment can turn into an employment relationship. Two IT specialists worked there formally under contracts for work. They were employed by service providers, so they were not freelancers. The Baden-Württemberg Regional Labor Court classified the contracts as sham contracts and upheld their claim for an employment relationship with the car manufacturer (judgment of 1 August 2013, 2 Sa 6/13). At first instance, the two had lost before the Stuttgart Labor Court. The subsequent proceedings before the Federal Labor Court ended without a judgment.
The pattern resembles false self-employment: the car manufacturer used the two like its own staff without being their employer. These points mattered most to the court:
- Instructions bypassing the ticket system: The car manufacturer had introduced a ticket system precisely to avoid this risk. In practice, however, the specialists kept receiving tasks directly from staff, including electronically.
- Integration: The two worked for a long time on the group’s premises, with its equipment, often at fixed times and closely networked with permanent employees.
- Labor instead of a work result: The car manufacturer had never asserted warranty claims. For the court, this indicated that it had bought labor rather than a work result.
One of the judgment’s guiding principles sums it up: “For the legal distinction between a contract for work or services and temporary agency work, only the actual performance of the contract is decisive.” (our translation) What counts is not how a contract looks on paper but how it is lived. For employment contracts, this principle has been written into law since 2017 (Section 611a BGB).
What clients can learn from this: temporary agency work and hiring freelance experts are two different things. The indicators used to tell them apart are similar, though: instructions and integration. A ticket system and a clean contract only help if everyday work matches them. So avoid giving freelancers instructions wherever possible. Our article When Does Employee Leasing Pay Off and When Do Freelancers? explains how employee leasing and hiring freelancers differ.
4. Status Determination Procedure: What It Offers and the Case Against It
In the status determination procedure under Section 7a SGB IV, the clearing office of Deutsche Rentenversicherung Bund decides whether an assignment is employment or self-employment. Since 1 April 2022, it only determines this employment status, no longer compulsory insurance in the individual branches of social security (DRV glossary on the procedure, in German). Other social insurance bodies are bound by the decision.
Both the client and the freelancer can apply, each on their own. An application is ruled out once the health insurance fund or the German Pension Insurance has already started proceedings, for example during an employer audit.
What Has Changed Since April 2022
- Forecast decision (Prognoseentscheidung): You can have the status clarified before the project starts. It is based on the written contract and the planned way of working. If any of this changes in the first month, you have to report it.
- Group assessment (Gruppenfeststellung): Once there is a decision on one specific assignment, the client can request an expert opinion for identical assignments, meaning the same work under the same circumstances and uniform contract terms. Each freelancer receives a copy when the contract is signed. If the opinion confirms self-employment, it protects you from back claims for the past on identical assignments you sign within two years of the opinion. The condition: the freelancer has their own cover against illness and for old age.
- Three-party arrangements: If a freelancer works for you through a service provider or agency and there are indications of instructions and integration at your company, the German Pension Insurance also checks whether they are actually employed by you. As the end client, you can then apply yourself.
- Oral hearing: In objection proceedings, you can request an oral hearing.
These four changes are temporary and apply until 30 June 2027 (Section 7a(7) SGB IV). Whether they will continue after that had not been decided as of October 2026.
Is an Application Worth It?
Applying is voluntary. The German Pension Insurance advises clients to start the inquiry procedure in cases of doubt (DRV glossary, in German). Timing matters:
- Before the project starts: With a forecast decision, you know where you stand in advance and can set up the assignment differently if needed.
- In the first month: If you apply within one month of the start and the German Pension Insurance finds employment, compulsory insurance only begins with the decision. Conditions: the freelancer agrees and is covered against illness and for old age for the period in between (Section 7a(5) SGB IV).
- Later: This protection no longer applies. If the German Pension Insurance finds employment, it applies from day one.
Freelancers weigh things differently. If the German Pension Insurance finds employment, their self-employment ends for this assignment, with the consequences described in section 3. Based on his experience, Sören Elser, founder and managing director of ElevateX, advises against applying:
In Sören’s view, the procedure makes no sense for the freelance assignments that ElevateX arranges. He bases this on his experience: once a freelancer is already working on an assignment, there is a risk that the German Pension Insurance will classify them as an employee. He considers the bar for being recognized as self-employed in the procedure to be high, and being classed as an employee is exactly what freelancers want to avoid. His advice: better not to apply.
Since either side can apply alone, talk early on about how you want to handle the topic. Sören’s assessment is not legal advice. A lawyer specializing in social security law can help with questions about your assignment.
5. How Can You Avoid False Self-Employment?
Clients and freelancers share responsibility for this. If both stick to a few clear rules, nothing stands in the way of a successful collaboration.
Tips From Practice
Prevention starts at the first meeting between freelancer and client: Are both aware of the risks? Do both know how to behave during the project? During onboarding and offboarding, you then clarify how you will work together without creating an employment relationship. Our article on freelancer onboarding shows how.
You can read more about successful collaboration in our success stories.
Our founder and managing director Sören Elser has been working with freelancers for many years. These are his most important tips:
- Awareness Companies need to know the differences between employees and freelancers. It is simply wrong to think you can “treat everyone the same” when it comes to false self-employment.
- Focus on result-oriented work Make sure you do not give freelancers instructions the way you would give them to employees. As a company, you should not care when, where and how someone works, but which results you need and how to reach them as quickly as possible.
- Location-independent working Location-independent work is central. Of course, this does not always work, and sometimes the freelancer has to be on site. Still, a free choice of workplace is a strong indicator of self-employment.
- Hourly rates A freelancer must earn more than a comparable employee. They have a completely different cost structure and, for example, have to fund their retirement entirely on their own. Our price guide for hiring freelancers shows what this means for your budget.
- Number of projects It helps if the freelancer has more than one project per year. Many freelancers follow the 80/20 rule: 80% of revenue from the main project, 20% from another project. This is a rule of thumb, not a legal threshold.
Best Practices
-
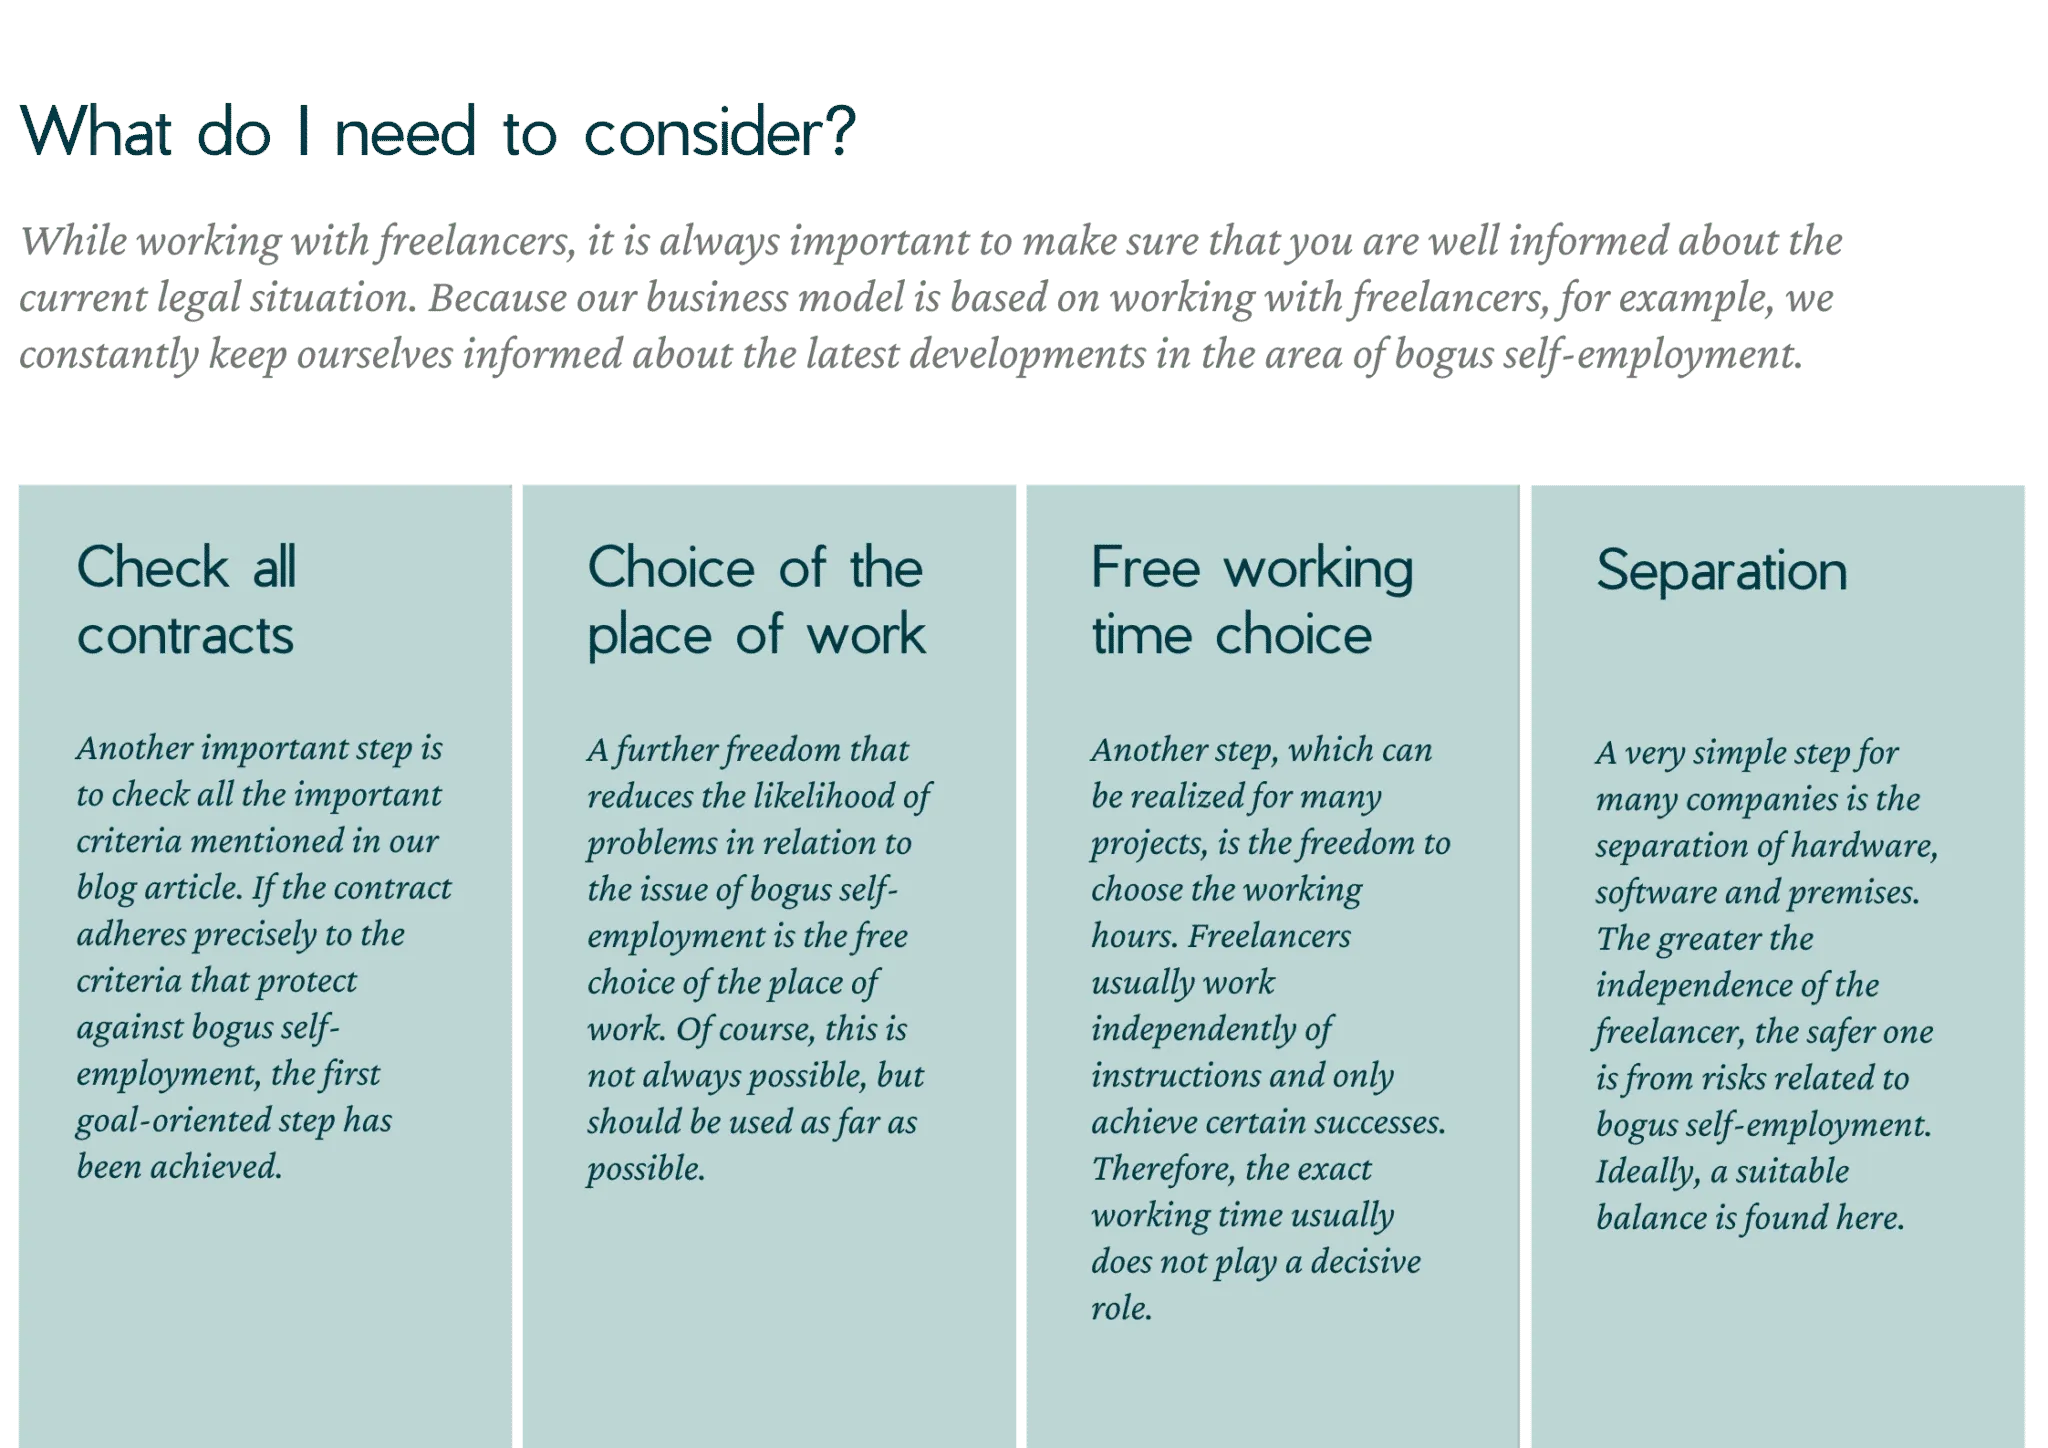
Ignorance does not protect from punishment: Whether you are a client or a freelancer, you have to obtain the necessary knowledge about false self-employment yourself. If you are unsure about the legal situation, get advice from experts such as a lawyer.
-
Review all contracts: Compare the criteria from section 2 with everyday work and the contracts. Does the freelancer have freedom of decision and bear entrepreneurial risk? The contract should state that the freelancer is not subject to instructions. It can also require the freelancer to regularly provide evidence of other assignments and of their own insurance cover. Our freelancer contract guide shows what else belongs in the contract.
-
Separation of hardware, software and premises: Companies and freelancers should not use the same hardware, software and premises but work independently of each other.
-
Free choice of work location and working hours: The more freely freelancers decide where and when they work, the lower the risk of false self-employment. You agree on results; how to get there is up to the freelancer.
Checklist for Clients: How to Spot Bogus Self-Employment
Ask yourself these questions before signing a contract and regularly during the project. If you answer “no” several times, rethink the collaboration or have it reviewed. The list is not exhaustive.
- Does the freelancer set their own working hours?
- Do they choose where they work, as far as the project allows?
- Are their tasks clearly separate from those of your employees?
- Do you manage through goals and results rather than individual instructions?
- Do they use their own hardware and software, without control by you?
- Do they present themselves as self-employed, for example by working for other clients?
- Are they free in how they report on their work?
- Is their fee well above the salary of comparable employees?
- Is the assignment described as a project with a clear goal and end?
- Does the way you actually work together still match the contract?
6. What Does ElevateX Do Regarding False Self-Employment?
Knowledge Transfer and Education
As soon as a collaboration takes shape, we explain the risks of false self-employment to our clients. If anything is unclear, we advise clients and freelancers. Thanks to our many years of experience, we can assess many situations and possible risks.
Reviewing the Criteria Together
If you need more extensive support, we review the criteria from this guide together with you and the freelancer, such as the 80/20 rule. Some uncertainty in your first projects with freelancers is completely normal. We think this caution is appropriate, because it means critical points are checked twice. This does not replace legal advice.
Do you have questions about a project and possible risks of false self-employment? Feel free to contact us. We will advise you and work with you to find the right approach for your project.
FAQs
What is false self-employment?
How do you recognize false self-employment?
What are the consequences of false self-employment?
What is a status determination procedure?
Is a good contract enough to avoid false self-employment?